
 Back


About this episode
Understanding Cash Flow and Debt Recovery
In this episode, Debbie Ray, a debt recovery case handler, and Jasmin Begum, a solicitor in the Dispute Resolution team, discuss the critical importance of maintaining healthy cash flow and preventing bad debts for businesses. They share practical tips on effective credit control, the significance of knowing your customers, and the steps to take when payments are late or disputes arise.
The conversation highlights the necessity of having clear contractual terms, maintaining thorough records, and acting promptly to mitigate risks associated with unpaid invoices. Listeners will gain insights into the debt recovery process, including when to seek legal advice and the implications of pursuing defended claims in court.


In this episode
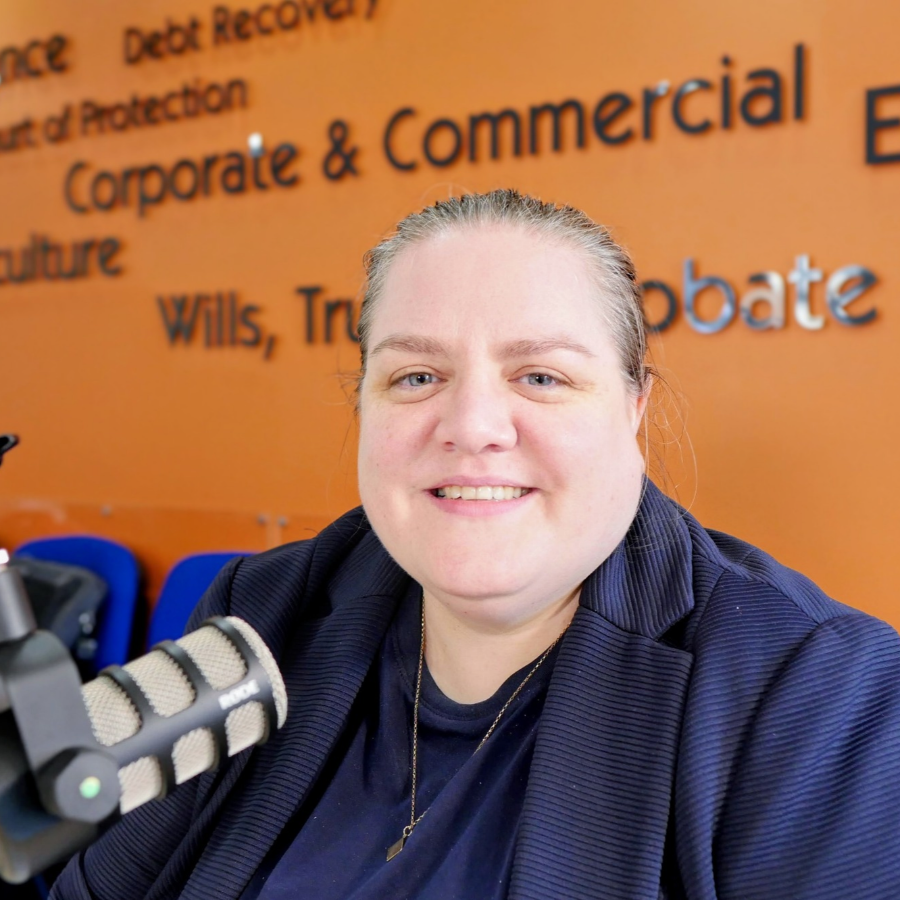
Debbie Ray
Following a career within retail, Debbie joined Lanyon Bowdler in September 2018 and currently works within our Debt Recovery Unit as a debt recovery case handler.
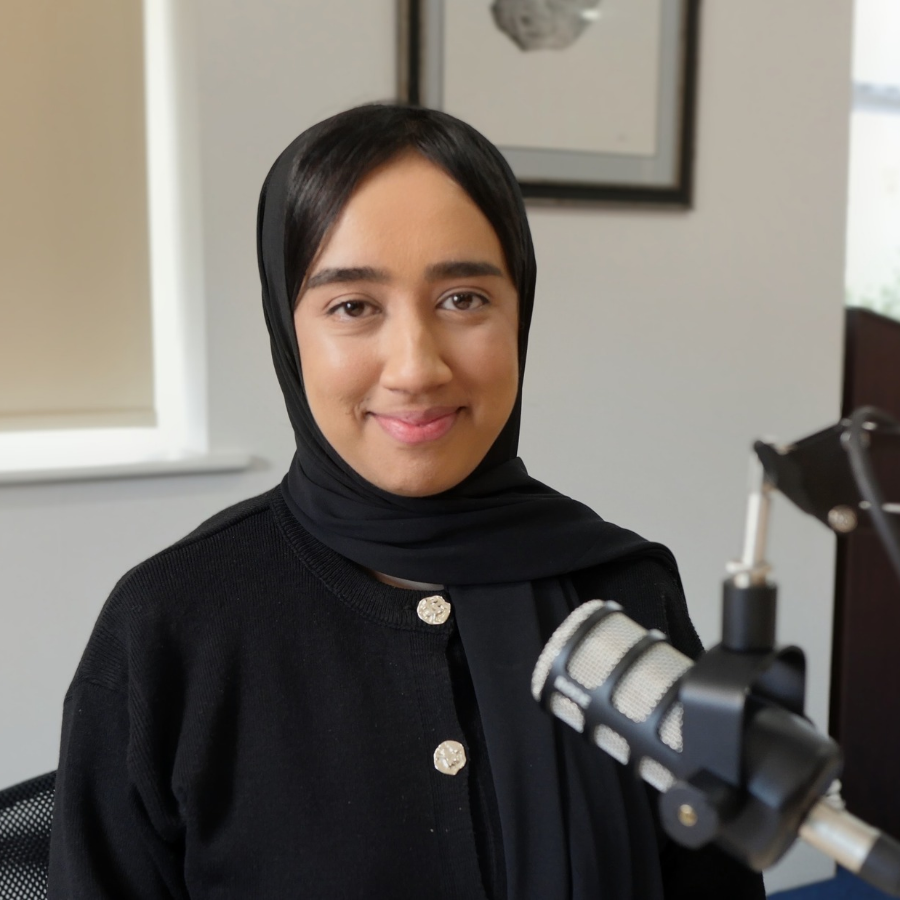
Jasmin Begum
Jasmin is extremely approachable and passionate about helping clients navigate their legal challenges and achieving the best possible outcomes.
Podcast transcription
[00:00:00 – 00:00:13] Introducer: This is The Legal Lounge from Lanyon Bowdler Solicitors, where you’ll hear about many aspects of law in England and Wales with special guests, industry experts and local charities. Here’s your host, Amanda Jones.
[00:00:13 – 00:00:48] Amanda: Hello and welcome to the Legal Lounge where we now release new episodes every Monday. If you haven’t heard previous shows there’s plenty of content for you.
[00:00:48 – 00:01:05] Debbie: Hello, I’m Debbie Ray. I’m a debt recovery case handler here at Lanyon Bowdler and we’re here today to discuss the importance of cash flow and preventing bad debts. Hopefully we can share some hints and tips with you to help ensure adequate cash flow and prevent bad debts. We’ll also touch on some options available to you should you need to pursue a debtor.
[00:01:04 – 00:01:14] Jasmin: Hi, my name is Jasmin Begum and I’m a solicitor in the Dispute Resolution team. So I will come at this slightly differently from the Dispute Resolution side. Ideally, good credit control means a matter never reaches me.
[00:01:13 – 00:02:58] Debbie: me. But sometimes what starts as an unpaid invoice develops into a genuine dispute. Perhaps a customer says the work was effective, the price wasn’t agreed or they didn’t authorise particular work. So I’ll touch on what businesses can do to put themselves in a stronger position if a dispute does arise and some of the risks and practical considerations if court proceedings become necessary. It’s important to understand why cash flow is important. Poor cash flow is one of the leading causes of business failure. not necessarily due to a lack of work or profit. You can be profitable on paper but still struggle if payments from customers are late. Late payments can create pressure on paying your wages of your staff, paying your suppliers, you yourself may experience interest and additional cost penalties and day-to-day running costs. Healthy cash flow gives you breathing space, it helps to absorb late payments without immediately feeling the impact. The importance of credit control is not just about chasing overdue invoices, of course that is important. But it’s also about knowing your customers, making informed decisions about credit, monitoring your accounts regularly and keeping a close eye on payment behaviour, ensuring that you invoice or bill in a timely manner and at the right time. Acting early when issues arise can help to minimise risk of bad debts. Understanding who you’re dealing with is so important. It helps in deciding on who to give credit to, who to ask for payment on account. If people are late paying, why are they paying late? Does this indicate a problem with their cash flow that could… that could potentially impact yours, and also acting quickly in the event that invoices are not paid is also really important. As Debbie mentioned, acting early is important from a dispute’s perspective as well. The longer a problem is left, the more difficult it can become to establish what happened. Staff may leave, documents can become harder to locate, and people’s recollections inevitably fade. So even where there is no immediate intention to issue proceedings, it is sensible to deal with a problem while the evidence is still readily available.
[00:02:57 – 00:02:58] Debbie: available.
[00:02:57 – 00:03:45] Debbie: Knowing your customers is also important. Remember to ask for the legal status of your customer. Are they a private individual? Are they a partnership? Are they a sole trader? Are they a limited company? Or are they an LLP? Consider asking them to complete a customer or credit application form to gather this information. If they’re an existing customer, don’t be afraid to request that their details are correct. Has their address changed? Has a partner left the business? GDPR obligates you to ensure that data held. how is up to date in any event. Knowing your customers at the outset of the matter aids with making informed decisions on credit. Sole traders are personally liable for the debts incurred in running their business. Same with partnerships, the usual position is that each partner is personally liable for business debts, and in the case of limited companies and LLPs, verify the information that you’re given from Companies House. You can readily do this by looking online.
[00:03:44 – 00:03:50] Jasmin: Following on from what Debbie has said, knowing exactly who you are dealing with becomes particularly important.
[00:03:49 – 00:04:17] Debbie: important if you ultimately need to pursue them. If you bring a claim, you need to identify the correct person or legal entity that actually owes the money. A trading name, for example, is not necessarily a separate legal entity. So, if you are dealing with a limited company, obtain its full company name and the company number. Company names can change, whereas the company number remains the same. If you are dealing with a sole trader or partnership, make sure you have the appropriate names and addresses. It is much easier
[00:04:16 – 00:04:25] Jasmin: It’s easier to obtain that information at the beginning of the commercial relationship than two years later when you are owed money and trying to work out who you’re actually contracted with.
[00:04:24 – 00:04:51] Debbie: The important question is who actually pays your invoices. Sometimes your contact isn’t necessarily the person who does pay your invoices. Sometimes when they’re late being paid, it’s because you haven’t sent it to the correct person or the correct department. Don’t be afraid to ask who processes your payments. Who would you need to send those invoices to? It also then gives you a point of contact if your invoice is late and remains outstanding. Remember, the correct department can equal fewer delays.
[00:04:50 – 00:05:02] Jasmin: It also helps to establish who actually has authority to place orders or approve additional work, because that can become important if the customer later says that particular work was never authorised.
[00:05:01 – 00:05:43] Debbie: The most important thing to do is to always do your research beforehand. Make sure you know what your customer actually does, not only from a business relationship perspective, but also from an invoicing perspective. How long have they been trading? Ask maybe for some trade references or do some credit checks and trust your instincts. If in doubt, always consider asking for payment up front. Sometimes this is the safest option, especially for high value work or work that’s being done one off. Remember to set credit limits. Decide whether to offer credit in the first place, irrespective of whether you’ve worked with them in the past. set a clear credit limit and use that as a control tool and make sure that you stick to it. Use it as an early warning trigger before your debts can grow.
[00:05:42 – 00:05:59] Jasmin: On the point of credit limits, it’s worth noting that before extending significant credit, you should consider not only whether the customer is likely to pay voluntarily, but what the position would be if you eventually had to enforce against them. Obtaining judgement is one thing, however recovering the money is another.
[00:05:58 – 00:07:36] Debbie: The next thing to look at is always monitoring payment patterns. patterns. Once you’ve decided on credit limits, make sure that you monitor those payment patterns. Watch out for those slow paying customers. Any small delays may be a signal of bigger issues. They may not, but they could be. Ask questions early and don’t be afraid to ask them why. Why are they struggling? Perhaps maybe you can work with them. Those early conversations can help prevent disputes or non-payment. Make sure that you document any concerns that you’ve got. ensuring that you’ve got records for any future credit considerations for the same customer. Another useful tool can be a credit control policy. If you don’t have one, we’d seriously consider implementing one. Having written and clear guidance can be really useful. Make sure that you include steps or guidance to take for when payment is late, not just for yourself but maybe for your staff. Having a timetable for action is also really useful. Having a consistent approach across the business makes things so much easier. Ensure you do what you say you will do. Follow your own timetable. Keep your own promises to follow up. Remember, consistency builds credibility. Customers will also learn that your credit control is taken seriously. I know it’s difficult, but remember to try and remove emotion from those decisions. At least you can say that you are just following the policy. Another important thing to implement, if you haven’t already, is your terms and conditions. Remember to set payment terms clearly and avoid any open-ended. end at payment terms. Terms and conditions can also allow for recovery of interest and costs, and this is particularly useful in terms of recovery of pre-issue costs. Make sure they’re fit for purpose and up to date. Also consider any legislation changes. It may mean that your terms and conditions need to be updated or amended.
[00:07:35 – 00:08:39] Jasmin: From the dispute resolution side, one of the first questions we ask when a dispute comes to us is, what was actually agreed between the parties? Ideally, the important terms should be recorded in writing. writing i.e. what goods services are being provided, the price, when payment is due and what happens if payment isn’t made. Clear terms reduce the scope for arguments later about what the parties actually agreed. It is also important that your terms and conditions actually form part of the contract. Simply having terms on your website or sending them for the first time with an invoice after the work has been completed does not necessarily mean these terms have been incorporated. Stated, ideally, the customer should be provided with the terms before the contract is entered into. We appreciate, however, that not every contract will be or is in writing. Agreements can be and are sometimes made verbally. The difficulty from a litigation perspective is proving what was agreed if the parties later give completely different accounts that can make a relatively straightforward debt much more fact-sensitive, uncertain and expensive to resolve.
[00:08:38 – 00:08:53] Debbie: If you are going to put things in writing, it’s always important to make sure that you’ve got a paper trail. As Jasmine says, this can be really useful if anything is ever disputed. Paperwork will differ from business to business and customer to customer. but always ensure that you have adequate copies.
[00:08:53 – 00:10:12] Jasmin: The reason why it is important to retain evidence is because it can be extremely helpful in avoiding disputes. If somebody comes to us and says, I’m owed £20,000, we need to establish why they are entitled to that £20,000 and what evidence proves it. We may be looking for the quotation or contract, terms and conditions, purchase orders, invoices, emails and messages, delivery notes. job sheets, photographs and anything else showing what was agreed and the goods or services that were provided. It is worth remembering that if you bring a claim you have to prove your entitlement to the money. An unpaid invoice on its own may not be sufficient if the customer is genuinely disputing the underlying contract. Additional work is a common area for disputes. The original job may have been clearly agreed but somebody then asks for something extra. and nobody records who authorised it or what it could cost. If additional work or a variation is agreed verbally, follow it up in writing, even if that is simply an email confirming what has been agreed and the additional cost. That can avoid a substantial evidential dispute later. If you see a dispute developing, preserve the evidence. Do not just keep the invoice, keep the relevant emails, messages, photographs and records. If there has been an important telephone conversation, make a note of it while it is still fresh in your mind.
[00:10:11 – 00:10:32] Debbie: It’s also important to know what to do when a customer payments are late. Avoid accepting vague or open-ended promises such as, I will pay it when I have the money. Always ask them when this will be, ask them when they can make the payment, agree a clear deadline and follow up immediately if it’s missed. If you agree a payment plan with your customer, try and ensure that it’s in writing.
[00:10:31 – 00:11:20] Jasmin: You may consider when that recovery becomes a dispute, there is also an important distinction between somebody who simply hasn’t paid and somebody who is actually disputing liability. If they say, for example, But that the goods were defective, the work wasn’t completed properly, the price wasn’t agreed, additional works wasn’t authorised, or that they have a claim of their own which they want to set off against the invoice, you may no longer be dealing with a straightforward debt recovery. You potentially have a contractual dispute. At that stage, we need to look at what was agreed, whether each party complied with their obligations and what evidence supports each side’s position. Remember, once a dispute starts developing… Be careful about what is put in writing. Emails and messages exchanged at that stage may ultimately form part of the evidence before the court. It is also therefore important to keep communications factual and professional.
[00:11:19 – 00:11:51] Debbie: Another thing to consider is whether you can ever recover any interest or costs at pre-action stage. That’s a stage before a claim is even issued in court. Make sure you check your contract in terms and conditions. You’ll be surprised how many businesses do not actually realise that they have to. They have the right to charge interest and slash all costs. These costs may be recoverable at pre-action stage, so why not take advantage of that? Consider using the late payment of Commercial Debts Interest Act 1998. This only applies to business-to-business debts, and if there’s no existing contractual clause. So if you’re dealing with private individuals, this would certainly not apply to you.
[00:11:51 – 00:12:12] Jasmin: If the matter has become litigated, costs recovery depend on the type and value of the claim and how it is dealt with. with by the court. In particular, if a matter is allocated to the small claims track, recovery of legal costs is generally very limited, so there always needs to be a commercial assessment of whether the amount being pursued justifies the likely cost of pursuing it.
[00:12:11 – 00:12:31] Debbie: The important question to ask yourself is when to seek help. This can be difficult. There’s no hard and fast rule for dealing with debt. But the earlier it’s possible helps to prevent the escalation. Don’t let your debts drift. Knowing your options can also help. and also be really helpful. Make sure that you build a relationship with the Debt Recovery Specialist so that you know who to turn to when you do need help.
[00:12:30 – 00:13:17] Jasmin: On the topic of knowing when to seek help, I will address the types of warning signs you should look out for. These might include repeated broken promises to pay. Somebody suddenly becoming difficult to contact, a previously good customer consistently paying late, or allegations suddenly being raised about the goods or services when payment is chased. If a genuine dispute is developing, taking advice early can help identify the issues and the evidence that may be needed before positions become entrenched. I do want to make clear that seeking legal advice does not necessarily mean issuing court proceedings. Your legal representation may suggest Just other avenues to try and reach settlement and litigation is viewed as a last resort. Sometimes a letter of claim may have the desired effect or negotiation or mediation may produce a quicker and more commercially sensible outcome.
[00:13:16 – 00:14:09] Debbie: I just wanted to run briefly through the steps of an undefended debt claim. An undefended debt, in any debt where a debt is not disputed. The first step is always to take pre-action. That involves writing a letter of claim or a letter before action. The type of letter of claim or letter before action will depend on the type of customer that you have and the type of business that you operate. If there’s no response to that letter and you cannot reach an agreement, it may be that issuing court proceedings is the next step. If there’s no response thereafter, you can then obtain what’s known as a judgement in default. Once you get that judgement and if it’s still unpaid, Then you’ve got the option of enforcing that judgement. There are various different methods as to how to enforce a judgement. Please remember to be aware of the limitation periods for debts. This is a time period whereby action should be taken, otherwise you may be barred from bringing a claim or you may require permission from the court.
[00:14:08 – 00:15:00] Jasmin: Debbie has explained the process for pursuing an undefended claim where the debtor doesn’t respond to the proceedings and it may be possible to obtain judgement in default. But what happens if the debtor does respond and defends the claim? and for claim. This is where matters can become more complicated. The debtor might argue that the goods were defective, the services weren’t carried out properly, the amount charged was not agreed or that they have a counterclaim. At that point we’re no longer dealing with a straightforward debt recovery matter. We need to consider the underlying contract, the allegations being made and the evidence available to support the claim. Once a defence is filed the court will generally allocate the claim to a particular track. Track, depending on its value and complexity. There are four tracks, the small claims track, which generally deals with claims up to £10,000, the fast track, generally for claims between £10,000 and £25,000, the intermediate track,
Part 2 [00:15:00]
[00:15:00 – 00:17:18] Part 2 – Speaker 0: Relief are claims between £25,000 and £100,000, and the multi-track, which usually deals with higher value or more complex disputes. The court will then give directions for how the case should proceed. Depending on the track, this may involve exchanging documents, witness statements and potentially expert evidence before the matter can go to a final hearing or trial. One of the key considerations when pursuing a defended claim is costs. Risks On the small claims track, as mentioned before, recovery of legal costs is generally very limited. For fast track and intermediate track claims, fixed recoverable costs generally apply, with the amount recoverable depending on the track, complexity band and stage of proceedings. For multi-track claims, costs are generally assessed by the court. The important point is that even if you are successful, you may not recover all of your legal costs. And if you’re unsuccessful, you could be liable for some of the other party’s costs. There’s also the litigation risk itself. Just because you believe you are owed money does not automatically mean you will succeed. You need to prove your case and ultimately the court will make a decision based on the evidence. This is why having clear contractual terms and maintaining good paper trial, as we have discussed earlier, is so important. That said, not every defended claim needs to proceed to trial. To trial, there are opportunities to resolve matters through negotiation or mediation, and sometimes reaching a commercial settlement makes much more sense than incurring further costs and taking the risk of litigation. Ultimately, before pursuing a defended claim, it is important to consider the strength of the evidence, the likely costs, the risks involved, and whether there’s a real prospect of recovering the money if you obtain judgement. That is why seeking legal advice at an early stage is the best way to resolve. that age can be valuable particularly where a debt becomes genuinely disputed. Finally I think the main message from both the credit control and litigation perspective is that preventing bad debt starts long before an invoice becomes overdue. Know who you are contracting with, have clear terms, keep good records, monitor payment behaviour and act promptly when something changes. If a debt does become disputed or the normal credit control process If not going anywhere, getting advice at an appropriate stage can help you understand your options, the risks and whether pursuing the matter is commercially worthwhile.
[00:17:17 – 00:17:25] Part 2 – Speaker 1: If you do need support with debt recovery or dispute resolution, please feel free to visit our website for our contact details and drop us an email or give us a call.
[00:17:25 – 00:17:44] Part 2 – Speaker 2: Thank you to Jasmine and to Debbie. Get more proof that lawyers don’t bite. If you have a legal issue you’d like me to put to our team to cover in an upcoming In an upcoming episode, please let me know by visiting lblaw.co.uk forward slash knowledge where you can search for all our podcasts. That’s lblaw.co.uk forward slash knowledge.
[00:17:43 – 00:17:47] Part 2 – Speaker 3: That was the Legal Lounge from Lanyon Bowdler Solicitors.